A 13-week cash flow forecast is not simply a spreadsheet that predicts how much money a business will have in the bank. A good CFO uses it as a decision-making tool. It can reveal when to hire, whether payroll is sustainable, when to buy inventory, which suppliers to prioritize, whether capital expenditure can be funded, how aggressively to pursue growth, and how much cash the business should keep in reserve.
For business owners, the real value of a 13-week cash flow forecast is not knowing what cash might look like 13 weeks from now.
It is knowing what decisions need to be made today to protect cash 13 weeks from now.
What Is a 13-Week Cash Flow Forecast?
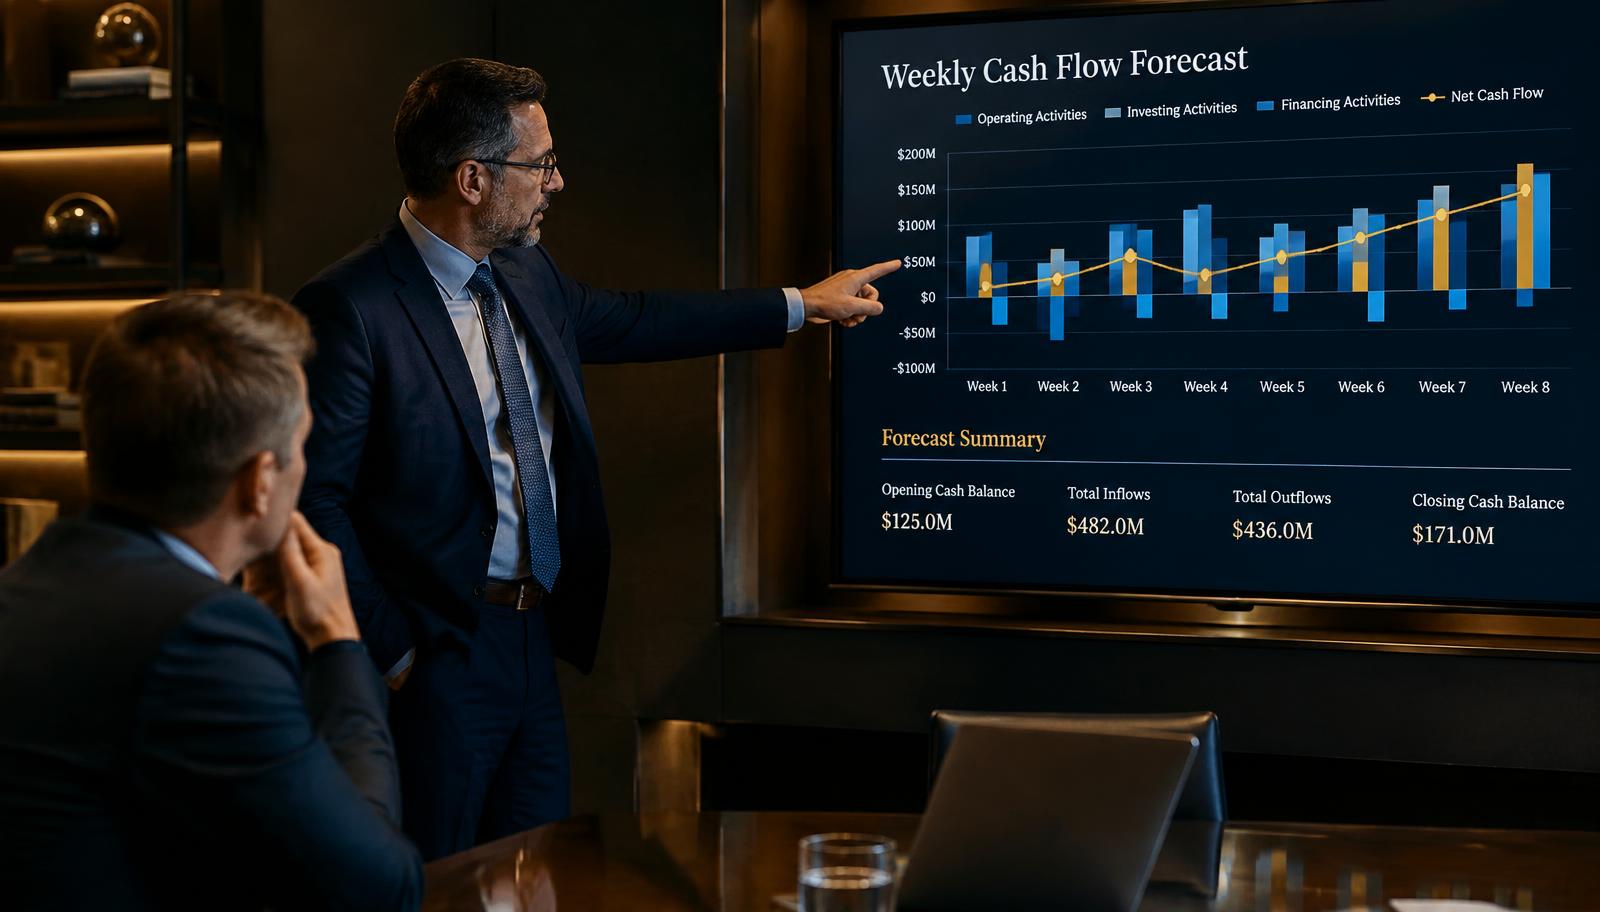
A 13-week cash flow forecast is a short-term financial planning model that projects a company's expected cash inflows and outflows, typically on a weekly basis for the next 13 weeks.
Unlike an annual budget, which is designed to provide a broader financial plan, a 13-week forecast focuses on cash timing and liquidity.
A typical forecast tracks:
| Cash flow area | What the CFO is looking at |
|---|---|
| Opening cash | How much cash is actually available today? |
| Customer collections | When is revenue expected to turn into cash? |
| Payroll | Can upcoming payroll obligations be comfortably funded? |
| Supplier payments | Which payments are due and when? |
| Inventory | When will cash be tied up in stock? |
| Debt | What principal and interest payments are coming? |
| Capital expenditure | Which planned investments require cash? |
| Taxes | What tax obligations are approaching? |
| Other operating costs | What recurring or unusual payments are expected? |
| Closing cash | What should the bank balance look like each week? |
The important distinction is that profit and cash are not the same thing.
A profitable business can run into a cash crisis if customers pay slowly, inventory grows too quickly, suppliers demand shorter payment terms, or large expenses arrive before the corresponding revenue is collected.
Why Do CFOs Use a 13-Week Cash Flow Forecast?
A CFO uses a 13-week cash flow forecast to create visibility over the company's near-term liquidity and financial flexibility.
That visibility supports decisions such as:
Can we afford to hire this person now?
Can we increase wages?
Should we delay a nonessential purchase?
Can we take on another major customer?
Should we place the inventory order?
Can we pay this supplier early?
Should we negotiate longer payment terms?
Can we fund this equipment purchase?
Do we need additional financing?
Are collections happening quickly enough?
How much cash should we keep untouched?
The forecast effectively turns cash from something that is reported after the fact into something management can actively manage.
That is the difference between accounting for cash and managing cash.
How Does a CFO Actually Use a 13-Week Cash Flow Forecast?
1. How Does the Forecast Affect Hiring Decisions?
Hiring is often treated as a growth decision.
From a CFO's perspective, it is also a cash commitment.
The salary is only one part of the calculation. A new employee can create additional costs through payroll taxes, benefits, equipment, software, recruitment fees, training and other overhead.
A CFO therefore asks:
When does this hire start consuming cash, and when should the additional revenue or productivity begin contributing to cash flow?
For example, a business may be profitable and growing, but if hiring three employees simultaneously creates a cash deficit in weeks six through ten, the timing of the hires may need to change.
The decision may not be:
"Can we afford the employees?"
It may be:
"Can we afford to hire all three at the same time?"
A 13-week forecast makes that timing visible.
2. What Does a 13-Week Forecast Tell a CFO About Payroll?
Payroll is one of the least flexible cash commitments for most businesses.
Employees expect to be paid on time regardless of whether customers have paid their invoices.
That makes payroll timing particularly important in a short-term cash forecast.
A CFO can use the forecast to identify:
upcoming payroll pressure
bonus or commission payments
seasonal payroll changes
planned wage increases
new employee start dates
contractor commitments
employer tax obligations
This can expose a problem before it becomes a crisis.
For example, if payroll is due on Friday but a large customer is not expected to pay until the following week, the business may technically be profitable while still facing a temporary liquidity problem.
The earlier that gap is identified, the more options management has.
3. How Does a CFO Use the Forecast to Manage Inventory?
Inventory consumes cash before it produces cash.
This is particularly important for businesses experiencing rapid growth.
Imagine a company wins a large new contract. Revenue projections look excellent, but fulfilling the contract requires a substantial inventory purchase.
The traditional question might be:
"How profitable is the contract?"
The CFO asks another question:
"How much cash will we have to put into this contract before we get paid?"
A 13-week forecast can show the timing of:
inventory purchase → production → delivery → invoice → collection
That timeline can reveal whether growth is creating a cash requirement that the business has not adequately funded.
This is one reason fast-growing businesses can sometimes experience greater cash pressure than slower-growing businesses.
4. Should We Pay Suppliers Early or Hold Cash?
Supplier payments are another area where CFO judgment matters.
Paying every supplier as soon as an invoice arrives may appear financially responsible, but it can unnecessarily reduce liquidity.
At the other extreme, consistently paying suppliers late can damage relationships, credit terms and operational continuity.
A CFO can use the forecast to segment payments.
For example:
Pay immediately
suppliers offering valuable early-payment discounts
critical suppliers where continuity is essential
obligations with significant penalties for late payment
Schedule strategically
suppliers with agreed payment terms
noncritical suppliers
expenses where timing can be managed contractually
The goal is not to delay payments indiscriminately.
The goal is to manage the timing of cash leaving the business without damaging the relationships that keep the business operating.
5. Can the Business Afford Its Planned Capital Expenditure?
A business may have a strong investment opportunity and still not have enough cash to make the investment safely.
This is where a 13-week forecast can improve capital expenditure decisions.
Before approving a major purchase, a CFO may examine:
current cash reserves
upcoming customer receipts
existing commitments
debt repayments
seasonal cash requirements
expected return from the investment
alternative financing options
The question becomes:
"If we spend this cash today, what does our liquidity position look like over the following 13 weeks?"
That is a much better question than simply asking whether the business can technically afford the purchase.
6. How Does the Forecast Help Manage Debt?
Debt creates fixed or scheduled cash obligations.
A CFO needs to understand not only the amount of debt outstanding, but also how debt service interacts with the company's weekly cash position.
The forecast can highlight:
principal repayments
interest payments
upcoming maturities
covenant-related requirements
refinancing deadlines
seasonal cash pressure
potential borrowing requirements
If the forecast shows a liquidity squeeze approaching, management has more choices when it acts early.
Those choices could include:
accelerating collections
reducing discretionary spending
renegotiating supplier terms
delaying capital expenditure
arranging a credit facility
refinancing existing debt
The worst time to look for financing is usually when the business is already running out of cash.
7. What Does a 13-Week Forecast Reveal About Collections?
One of the most valuable uses of a 13-week cash forecast is identifying whether sales are actually turning into cash quickly enough.
A business can report increasing revenue while simultaneously experiencing deteriorating cash flow.
That can happen when:
customers take longer to pay
invoices are issued late
disputes delay payment
credit terms are too generous
collections are inconsistent
large customers become increasingly concentrated
A CFO can compare expected collections against actual collections and identify whether assumptions are proving reliable.
This creates an important management metric:
How accurate are our cash collection assumptions?
If the business repeatedly expects $500,000 of collections and receives $350,000, the problem is not simply forecasting accuracy.
It may indicate an underlying accounts receivable problem.
8. Can a 13-Week Forecast Help Decide Whether to Pursue Growth?
Yes, and this is one of its most important strategic uses.
Growth consumes cash.
New customers can require:
additional employees
additional inventory
new equipment
additional vehicles
marketing investment
increased working capital
longer customer payment cycles
A CFO therefore evaluates growth through two lenses:
Profitability: Will this opportunity make money?
Liquidity: Can we fund the journey from investment to collection?
A contract that produces attractive margins may still create a significant short-term cash requirement.
The forecast helps management determine whether the company can safely absorb that requirement.
9. How Much Cash Should a Business Keep in Reserve?
There is no universal cash-reserve number that works for every business.
A business with predictable recurring revenue, fast collections and low fixed costs may require a different reserve from a business with seasonal revenue, high payroll commitments and significant inventory requirements.
A CFO considers factors such as:
revenue volatility
customer concentration
payroll obligations
supplier dependence
debt service
seasonality
inventory requirements
capital expenditure needs
access to financing
business growth rate
The 13-week forecast helps answer a more useful question:
"What is the minimum cash balance we are comfortable operating with under realistic conditions?"
That number becomes a management threshold rather than an arbitrary target.
What Happens When the Forecast Shows a Cash Shortfall?
The purpose of forecasting is not to produce a reassuring spreadsheet.
It is to identify problems early enough to do something about them.
If the forecast shows cash falling below the company's minimum acceptable level, the CFO can investigate the drivers.
For example:
| Problem identified | Potential management response |
|---|---|
| Slow customer collections | Intensify collections and review credit terms |
| Excess inventory | Reduce purchasing or accelerate inventory sales |
| Large upcoming payment | Renegotiate timing where commercially appropriate |
| Payroll pressure | Reconsider hiring timing or other workforce changes |
| Capital expenditure | Delay, phase or finance the investment |
| Debt pressure | Explore refinancing or alternative funding |
| Seasonal cash deficit | Arrange funding before the pressure arrives |
| Margin deterioration | Review pricing, costs and customer profitability |
The important point is that the forecast does not make the decision. It gives management better information with which to make the decision.
What Michael Minnaugh Looks For When Reviewing a 13-Week Cash Forecast
The biggest mistake I see with cash forecasts is treating them as a spreadsheet exercise.
A 13-week forecast is only useful if the assumptions behind it are realistic.
When I review one, I am not just looking at the closing cash balance. I want to understand why the cash balance is moving and whether the assumptions are credible.
1. I Look at the Assumptions Behind the Numbers
If a forecast says a customer is going to pay $250,000 in week four, I want to know why.
Is there an invoice?
Has the customer historically paid on time?
Is there a dispute?
Has the customer confirmed the payment date?
The quality of the forecast depends heavily on the quality of its assumptions.
2. I Look for Timing Mismatches
A business can be profitable but still have a cash problem because money is coming in after the business has to pay its obligations.
I look closely at the timing between:
sales → invoicing → collection
and:
purchasing → payroll → supplier payment → debt service
That timing often tells you more about the immediate health of a business than the profit and loss statement alone.
3. I Look for Optimism
Forecasting naturally introduces assumptions.
The danger is allowing optimism to become a financial control system.
If every customer pays on time, every sales opportunity closes, every expense stays on budget and nothing unexpected happens, the forecast may look excellent.
That does not necessarily make it realistic.
I want to know what happens when assumptions are missed.
4. I Look for the Cash Conversion Problem
If revenue is increasing but cash is not, I want to understand why.
The problem could be:
inventory
payment terms
margins
customer concentration
operational inefficiency
That is where a forecast becomes a diagnostic tool rather than just a projection.
5. I Look at the Lowest Cash Point
The headline ending cash balance is not enough.
I want to know:
What is the lowest cash balance during the 13 weeks?
A business finishing the forecast with $1 million in cash could still face a serious problem if cash falls to $50,000 halfway through the period.
That low point may determine whether the business can safely make a hiring decision, purchase equipment, pay suppliers or take on additional work.
6. I Ask What Decision the Forecast Is Supposed to Support
This is probably the most important question.
A forecast should exist for a reason.
If management is considering a major hire, acquisition, equipment purchase, expansion, dividend, debt repayment or new customer contract, the forecast should help answer that specific question.
A forecast is most valuable when it changes a decision before the cash leaves the bank.
That is how I believe CFO-level financial management should work.
What Makes a 13-Week Cash Flow Forecast Useful?
A useful forecast has several characteristics.
It is current.
It is updated regularly rather than being created once and forgotten.
It is realistic.
Cash assumptions are based on evidence rather than wishful thinking.
It is granular.
Important receipts and payments can be identified rather than buried in broad monthly totals.
It is compared against reality.
Actual cash results are measured against the forecast so assumptions can improve over time.
It drives decisions.
Management uses the information to change actions.
It has clear ownership.
Someone is responsible for maintaining the forecast and challenging assumptions.
The sophistication of the spreadsheet is secondary.
A simple, accurate forecast that management actually uses is more valuable than a complex model filled with unreliable assumptions.
How Often Should a 13-Week Cash Flow Forecast Be Updated?
For businesses where liquidity is a significant management concern, the forecast should generally be updated at least weekly.
The process should involve:
Rolling the forecast forward.
Replacing assumptions with actual results.
Comparing forecast cash receipts with actual collections.
Updating upcoming payments.
Reassessing major assumptions.
Identifying the new minimum cash position.
Escalating emerging risks.
Making decisions based on the updated outlook.
This creates a rolling 13-week view rather than a static forecast.
Over time, this also creates something valuable: a record of forecast accuracy.
Management can begin to identify which assumptions are consistently too optimistic or conservative.
What Is the Difference Between a Cash Flow Forecast and a Budget?
A budget and a 13-week cash flow forecast serve different purposes.
| Budget | 13-week cash flow forecast |
|---|---|
| Usually annual | Rolling 13 weeks |
| Focuses on profitability and planning | Focuses on liquidity and timing |
| Often monthly | Usually weekly |
| Strategic planning tool | Short-term decision tool |
| Revenue and expense focused | Cash-in and cash-out focused |
| Measures financial performance | Manages cash availability |
A strong finance function uses both.
The budget answers:
"Where are we trying to go?"
The 13-week forecast answers:
"Can we safely get there from where we are today?"
When Should a Business Start Using a 13-Week Cash Flow Forecast?
A business does not need to be in financial distress to benefit from one.
It can be particularly valuable when a company is:
growing rapidly
hiring aggressively
carrying significant inventory
experiencing slower collections
taking on debt
making major capital investments
entering a new market
managing seasonal revenue
acquiring another business
experiencing margin pressure
preparing for a transaction
It is especially useful when management starts saying:
"We are profitable, but I don't understand why there isn't more cash in the bank."
That is often a signal that the business needs greater visibility into its working capital and cash conversion cycle.
What Should Business Owners Take Away From a 13-Week Cash Forecast?
A 13-week cash flow forecast should not sit inside the finance department as another reporting document.
It should become part of the management conversation.
The most useful questions are not:
"What will our cash balance be in 13 weeks?"
They are:
What is putting pressure on cash?
What assumptions are we relying on?
Where could the forecast be wrong?
What decision do we need to make now?
What happens if collections are slower than expected?
Can we afford this investment without compromising liquidity?
Are we growing faster than our cash can support?
What minimum cash reserve should we protect?
When used properly, a 13-week cash flow forecast becomes an early-warning system and a strategic decision tool.
Final Takeaway: Cash Forecasting Is About Decisions, Not Spreadsheets
The real value of a 13-week cash flow forecast is not the forecast itself.
It is the visibility it gives a business owner and management team before making decisions that affect cash.
Hiring, payroll, inventory, supplier payments, capital expenditure, debt, collections and growth all have one thing in common: they eventually affect the bank account.
A CFO's role is to understand those interactions before they become a problem.
At Sataurius Consulting, we help business owners turn financial information into better business decisions. From cash flow management and forecasting to accounting, tax, CFO advisory and strategic financial planning, our focus is on giving leadership teams the financial visibility they need to operate with greater confidence.
If your business is growing, facing cash pressure, or making significant financial decisions without a clear view of the next 13 weeks, a properly managed cash flow forecast can provide the visibility needed to act before the pressure becomes a problem.
Frequently Asked Questions
What is a 13-week cash flow forecast?
A 13-week cash flow forecast is a rolling weekly projection of expected cash receipts, payments and ending cash balances over the next 13 weeks. CFOs use it to identify upcoming liquidity pressures and make decisions around hiring, purchasing, debt, capital expenditure, collections and growth.
Why is a 13-week cash flow forecast important?
It gives management visibility into short-term liquidity. Unlike an annual budget, it shows when cash is expected to enter and leave the business, helping management identify potential shortages early enough to change spending, accelerate collections, negotiate payment timing or arrange financing.
Is a 13-week cash flow forecast only for businesses experiencing financial problems?
No. Healthy and growing businesses can benefit from one because growth itself consumes cash. A forecast can help management understand whether new employees, inventory, capital expenditure, acquisitions or large customer contracts can be funded without creating an unnecessary liquidity risk.
How often should a 13-week cash flow forecast be updated?
A rolling 13-week cash forecast is typically updated weekly. Actual receipts and payments should replace previous assumptions, while upcoming cash movements and assumptions are refreshed. Comparing forecasts with actual results also helps management improve the accuracy of future forecasts.
What is the difference between cash flow forecasting and budgeting?
A budget generally focuses on planned revenue, expenses and profitability over a longer period. A 13-week cash flow forecast focuses on the timing of actual cash receipts and payments over the near term. Businesses can use both tools together to manage profitability and liquidity.
Can a 13-week cash flow forecast help with hiring decisions?
Yes. The forecast can show the cash impact of salaries, payroll taxes, benefits and other employment costs alongside expected collections and other commitments. This allows management to determine not only whether a hire is affordable, but also whether the timing of the hire is appropriate.
What should a CFO look for in a 13-week cash flow forecast?
A CFO should examine the assumptions behind expected receipts and payments, the timing of cash movements, the lowest projected cash balance, forecast accuracy, working capital trends and potential downside scenarios. The goal is to identify decisions and risks before they affect liquidity.
When should a business consider getting CFO support for cash flow forecasting?
CFO support can be particularly valuable when a business is growing quickly, experiencing working capital pressure, taking on debt, making significant investments, managing complex cash flows or preparing for a transaction. The CFO's role is to connect the forecast to decisions rather than simply produce the numbers.